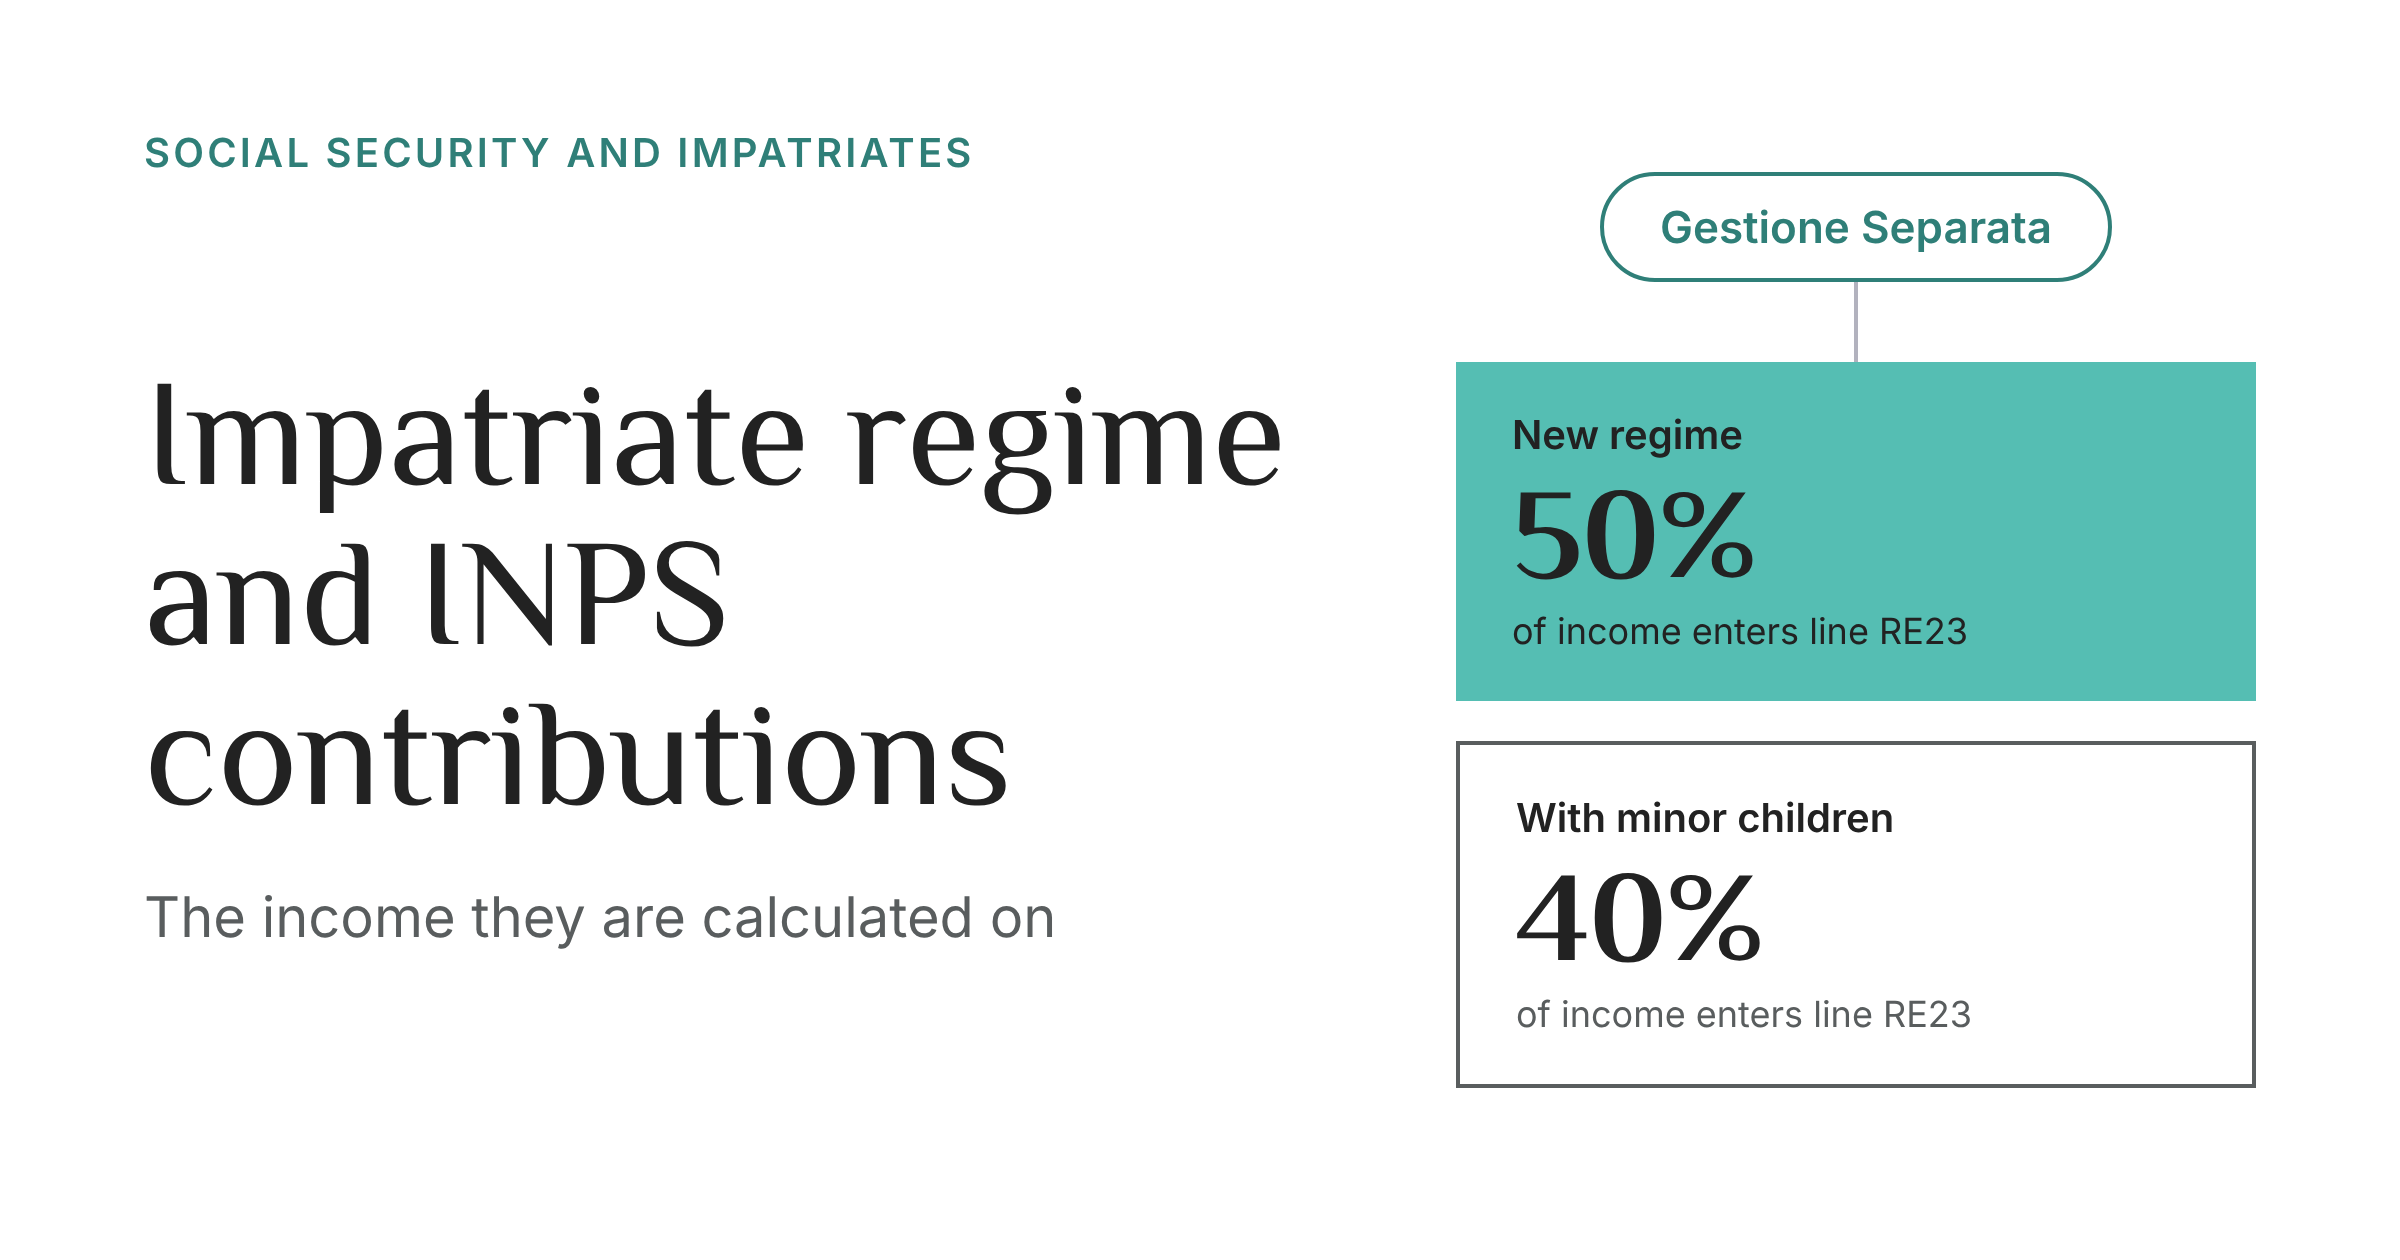
How much INPS do impatriates pay? A self-employed professional enrolled in the INPS Gestione Separata who applies the impatriate regime (regime impatriati) pays contributions at the rate in force for the year, on a base that is already reduced by the tax relief, not on full income. On €60,000 of income, at the 2025 rate of 26.07%, contributions under the new regime at 50% are €7,821 instead of €15,642.
The share of income that stays in the base depends on the code in the “Impatriati” box: 50% under the new regime of art. 5 of Legislative Decree 209/2023, 40% with minor children, 30% or 10% under the earlier regimes still running. The figure is read on line RE23 (or RE25) and carried to Quadro RR.
Where to start: Quadro RR
The contributions of anyone enrolled with INPS as a self-employed worker are determined in Quadro RR of the Redditi PF tax return. INPS explains how to fill it in every year in a dedicated circular: for 2025 income it is circular no. 62 of 27 May 2026, which also covers the balance for 2025 and the advance payment for 2026.
The form is divided into sections, and the circular says where each one takes its contribution base from:
- Section I, artisans and traders. The base is business income from Quadri RF, RG and RH. If the “Impatriati” box is ticked in Quadro RG, line RG34, column 3 is used instead of RG31, i.e. the relieved income; for Quadro RF the corresponding line is RF99, column 3.
- Section II, professionals in the Gestione Separata. The base is all self-employment income declared for IRPEF purposes. The circular refers to Quadro RE, lines RE23 or RE25.
- Sections III and IV. They cover amateur sportspeople and the general instructions for the Gestione Separata.
The income on which the contribution is calculated goes in column 11 of line RR5. Section II must be filled in even when income is zero or there is a loss.
For professionals the circular gives two rates for 2025, 24% and 26.07% (they change every year), depending on whether the person is covered by other compulsory social security. The first question in Quadro RR is therefore a different one: which line of Quadro RE does the income come from?
From RR to RE23 and RE25
For a professional in the Gestione Separata, Quadro RR refers back to Quadro RE. Two lines matter:
- RE23, income (or loss) from professional and artistic activities. It is the starting point for the contribution base.
- RE25, the difference between RE23 and RE24. Line RE24 holds the excess of losses from 2006 and 2007, which can be carried forward without time limit. If RE24 is filled in, the base is read on RE25. The INPS circular says so expressly: RE23, or RE25 if there are losses on line RE24.
The key is in the instructions for Quadro RE (Redditi PF 2026, booklet 3). When a code is entered in the “Impatriati” box in the margin of the form, line RE23 is no longer the plain difference between fees and expenses, but follows this logic:
- Take the income that does not benefit from the relief, i.e. foreign self-employment income and the part above the €600,000 limit or excluded because of the de minimis rules (columns 2 and 3 of line RE21, and the taxable part of column 4);
- Add to it the relieved percentage of the remaining income, calculated on the total of RE21 column 5 net of columns 2, 3 and 4;
- The result is the income shown on RE23, which then flows into Quadro RN.
In practice RE23 is already the income that counts towards the IRPEF taxable base, and the INPS circular takes it as the base for the contribution. The link between IRPEF and INPS does not come from a rule that states it: it comes from the fact that Quadro RR draws on the same line.
All scenarios: the codes in the “Impatriati” box
The share of income that remains in RE23 depends on the code entered in the margin of Quadro RE. The Redditi PF 2026 instructions provide eight codes for self-employed workers.
| Code | Regime | Share of income in RE23 |
|---|---|---|
| 1 | Art. 16 Legislative Decree 147/2015, version before Decree-Law 34/2019 (self-employed who start an activity; Law 238/2010 subjects with option) | 50% |
| 2 | Art. 16, paragraph 1, Legislative Decree 147/2015 | 30% |
| 4 | Art. 16, paragraph 5-bis, Legislative Decree 147/2015: relocation to Abruzzo, Molise, Campania, Puglia, Basilicata, Calabria, Sardinia or Sicily | 10% |
| 5 | Art. 16, paragraph 5-quater: professional athletes (contracts in place on 20 May 2022) | 50% |
| 6 | Relocation before 30 April 2019 with the option under the Revenue Agency order of 3 March 2021 | 50% |
| 7 | Same case as code 6, reduced relief | 10% |
| 8 | Art. 5, paragraphs 1, 2 and 3, Legislative Decree 209/2023: relocation from 2024, up to €600,000 a year | 50% |
| 9 | Same art. 5 Legislative Decree 209/2023, case with minor children | 40% |
For artisans and traders (section I) the mechanism is the same, but the base is read on lines RG34 or RF99, column 3, when the “Impatriati” box is ticked.
Example: same income, four scenarios
A professional in the Gestione Separata with no other compulsory social security cover, earning €60,000 of Italian self-employment income (RE21, column 5), with no part excluded from the relief. 2025 rate of 26.07% (INPS circular 62/2026), which changes from year to year. The example ignores the minimum and maximum contribution thresholds.
| Scenario | Code | Base in RE23 | INPS contributions |
|---|---|---|---|
| No regime | – | €60,000 | €15,642 |
| New regime, 50% | 8 | €30,000 | €7,821 |
| New regime with minor children, 40% | 9 | €24,000 | €6,257 |
| Pre-2024 regime, 30% | 2 | €18,000 | €4,693 |
| Pre-2024 regime, Southern Italy, 10% | 4 | €6,000 | €1,564 |
Watch out when part of the income is excluded from the relief. With €700,000 of income under the new regime, the portion up to €600,000 counts at 50% (€300,000) and the remaining €100,000 stays fully taxable: RE23 is €400,000, not €350,000. The contribution base follows the same calculation, within the annual maximum.
Why online sources contradict each other
Three reasons explain the divergence.
- The doubt was real. Before circular 52/2023 it was unclear whether the reduced income or total income mattered (so Fisco e Tasse). Part of the online content may still reflect that stage.
- The rule is confused with the tax return. Art. 5 of Legislative Decree 209/2023 speaks of total income for IRPEF and does not mention contributions. Anyone reading only the rule concludes that social security sits outside the relief. The link is in Quadro RR, which starts from RE23.
- Professional pension funds follow their own rules. Anyone working with a professional fund (Cassa), such as engineers, lawyers or accountants, follows the rules of that fund, which may not start from the reduced income.
Sources
- Art. 5 Legislative Decree no. 209 of 27 December 2023 (impatriate regime from 2024); art. 16 Legislative Decree no. 147 of 14 September 2015 (previous regime).
- Italian Revenue Agency, Redditi Persone Fisiche 2026 instructions, booklet 3 (Quadro RE, lines RE21, RE23, RE24 and RE25; “Impatriati” box).
- INPS, circular no. 62 of 27 May 2026 (Quadro RR, Redditi 2026-PF: sections I and II).
- INPS, circular no. 52 of 7 June 2023.
- Further reading consulted: Fisco e Tasse, Investireoggi, Fiscomania, NT+ Fisco, QuiFinanza, impatria.com.
This article is for information only and is not professional advice. The case is simplified and the rules must be checked as at the date of reading, including in relation to the professional fund of enrolment and the INPS circulars for the relevant year.